Romania’s real estate investment market attracted €691 million in the first nine months of 2026, up 64% compared with the same period last year and the strongest result for this interval since 2020, according to Colliers’ ”CEE Investment Scene Q1-Q3 2026” report. Romania thus recorded the third-largest volume among the six Central and Eastern European markets analysed, after Poland and the Czech Republic, and exceeded the average registered in the first nine months of 2015 – 2019. The result comes amid more challenging conditions, with higher financing costs and investors paying closer attention to property quality, income stability and long-term prospects, Colliers consultants point out.
Across the six Central and Eastern European markets analysed by Colliers – Bulgaria, the Czech Republic, Poland, Romania, Slovakia and Hungary – real estate investment reached nearly €8.8 billion in the first nine months of the year, 22% more than in the same period of 2025. Of this total, around €3.1 billion was transacted in the third quarter. Poland accounted for most of the growth, while Romania and Bulgaria also delivered strong results. In Romania’s case, the Q3 bias was even more visible, as this quarter represented more than half of the total volume seen for the Q1-Q3 period.
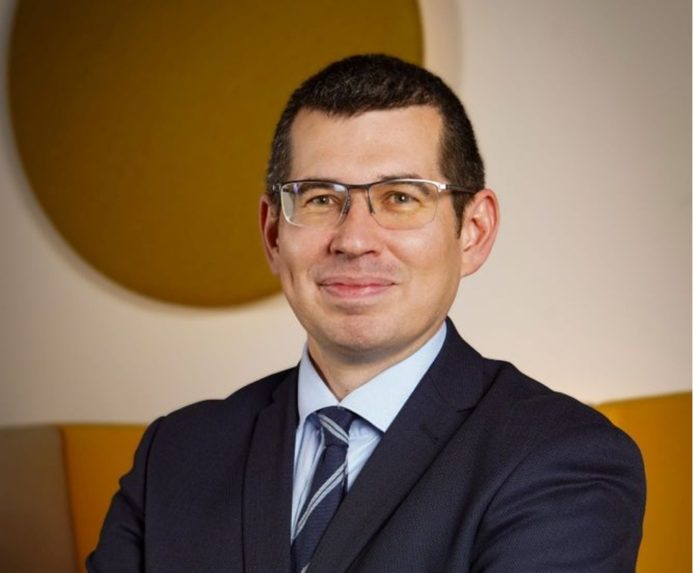
”Romania’s nearly EUR 700 million in the first nine months, up 64% and our strongest Q1-Q3 result since 2020, came at a time when financing is more expensive and investors are more selective, which makes the result more meaningful. With Colliers involved in approx. 60% of the reported Q1-Q3 volume, in six transactions, we see that capital is available for Romania. The numbers support this, prime Bucharest offices are still roughly 150 basis points above Warsaw and more than 400 basis points over the five-year euro swap. Across CEE, liquidity has been rebuilt, with regional buyers now accounting for close to half of all volume. Romania is on their path: the spread is there, and the depth is following”, says Robert Miklo, Partner, Head of Capital Markets, Colliers Romania.
Romania rises to third place in the region, after Poland and the Czech Republic
At regional level, Poland remained the largest investment market, with transactions totalling €4.7 billion in the first nine months, up 81% year-on-year and accounting for 54% of the total volume. The Czech Republic attracted nearly €2.1 billion, 18% less than in the same period of 2025, followed by Romania with €691 million. Hungary recorded €606 million, Bulgaria €472 million – its strongest result for the first three quarters – and Slovakia €216 million.
For Romania, the comparison with previous years points to a clear recovery in activity. Investment volume in the first nine months exceeded the average for the corresponding periods of 2015-2019, despite a more challenging economic environment and heightened political uncertainty. According to Colliers consultants, investors are increasingly assessing the potential of each property and sector rather than focusing solely on short-term economic developments. At the same time, large transactions can visibly alter quarterly results, particularly in smaller markets. A longer-term view is
therefore more relevant, and Romania’s first-nine-month result confirms an improvement compared with recent years.
Regional capital accounts for nearly half of CEE investment
At the same time, investors from Central and Eastern Europe are playing an increasingly important role in the market, with acquisitions of nearly €4.3 billion in the first nine months, equivalent to almost half of the total volume. Czech investors were the most active, with approximately €2.5 billion, followed by Hungarian investors with €806 million and Polish investors with nearly €500 million. In 2026, up to this point, amid a lack of major transactions, Romanian investors accounted for around €140 million of the year’s volume,.
An increasing share of these investments is crossing domestic market borders. Czech and Hungarian investors are acquiring properties in other Central and Eastern European countries, while some larger groups have also expanded into Germany and Austria, indicating that regional investors have reached a scale that allows them to compete for assets beyond their home markets.
International investors also remain an important presence in the region, with US capital accounting for acquisitions of nearly €1 billion, Israeli investors for approximately €684 million and German investors for €622 million. Alongside regional capital, this diversity of investment sources contributes to a more balanced market that is less dependent on a single investor category, Colliers consultants note.
In terms of property types, offices and retail attracted the largest volumes in the first nine months, at approximately €2.5 billion each, representing 30% and 29% of the total, respectively. The industrial and logistics sector attracted nearly €1.7 billion, while the residential segment exceeded €1 billion. Across all these sectors, investors are paying closer attention to location, tenant quality, income stability and the capital expenditure properties will require in the coming years.
In retail, investors remain interested in retail parks and grocery-anchored properties, which provide more stable income. Shopping centers are also returning to investors’ radar where pricing has adjusted, and there is scope to improve performance. In the office market, well-located and competitive buildings are preferred, while the industrial and logistics sector continues to be supported by manufacturing investment, the relocation of operations closer to European markets and the need for more resilient supply chains.
At the same time, the European real estate market is facing several pressures. The most frequently cited are construction costs and sector inflation, geopolitical tensions and high interest rates, mentioned by 62%, 59%, and 57% of respondents, respectively. Access to financing is less of a concern than in the past; the key challenge is whether an investment can generate a sufficient return under current market conditions.
Bucharest yields remain above those in the region’s main markets
Against this backdrop, Bucharest continues to offer higher yields than markets such as Warsaw or Prague. At the end of the third quarter, prime yields stood at approximately 7.5% for offices, 7.75% for
industrial and logistics properties, and 7.25% for shopping centers. These levels can help maintain Romania’s appeal to investors, although yields are now assessed alongside other factors, including financing costs, rental growth and the risks associated with each investment.
Financing remains available for good properties and strong investors, but the cost of capital matters more than it did in the past, the Colliers report shows. In these conditions, buyers are looking for properties with the potential to grow income over time through higher rents, lease indexation, attracting new tenants or more efficient management. By contrast, properties whose value depends primarily on a return to cheaper financing are more difficult to transact.
The report also shows that higher transaction volumes in the region have not led to a broad-based compression of yields. Investors are willing to buy where there are clear prospects for income growth and where the property’s price can be supported by its long-term performance.
”Yields remain an important advantage for Romania, but investors are looking at the full picture: financing costs, the income a property can generate, the investment required to keep it competitive, and sometimes the strategic nature of the investment. The market is more selective, but there is an appetite for good properties with robust long-term prospects”, adds Robert Miklo.
According to Colliers, the first-nine-month results show that Central and Eastern Europe continues to attract investment even in a more challenging financing environment, supported by the growing activity of regional investors and interest in properties capable of generating stable long-term income. Romania is among the markets that performed well in 2026, with investment volume clearly above the previous year’s level. For the full year, Colliers consultants estimate that investment will reach approximately €12.5 billion across the six markets analysed, compared with €11.6 billion in 2025. If the forecast materialises, the region will end 2026 with a higher transaction volume, even though financing remains more expensive than during the years of very low interest rates.
About Colliers
Colliers (NASDAQ, TSX: CIGI) is a global diversified professional services and investment management company operating through three industry-leading businesses: Commercial Real Estate, Engineering and Investment Management. With greater than a 30-year track record of consistent growth and strong recurring cash flows, we scale complementary, high-value businesses that provide essential services across the full asset lifecycle. Our unique partnership philosophy empowers exceptional leaders, preserves our entrepreneurial culture, and ensures meaningful inside ownership – driving strong alignment and sustained value creation for our shareholders. With $6 billion in annual revenues, 28,000 professionals, and $110 billion in assets under management, Colliers is committed to accelerating the success of our clients, investors, and people worldwid